Hourly or Fixed Fee? What Actually Decides Which One Costs You Less
The received wisdom says hourly billing rewards slowness and a fixed fee protects the buyer. What really decides the cheaper arrangement is who is carrying the uncertainty, and when you pay.
- Business
- Farah Siddiqui
- 1,010 words, 4 min
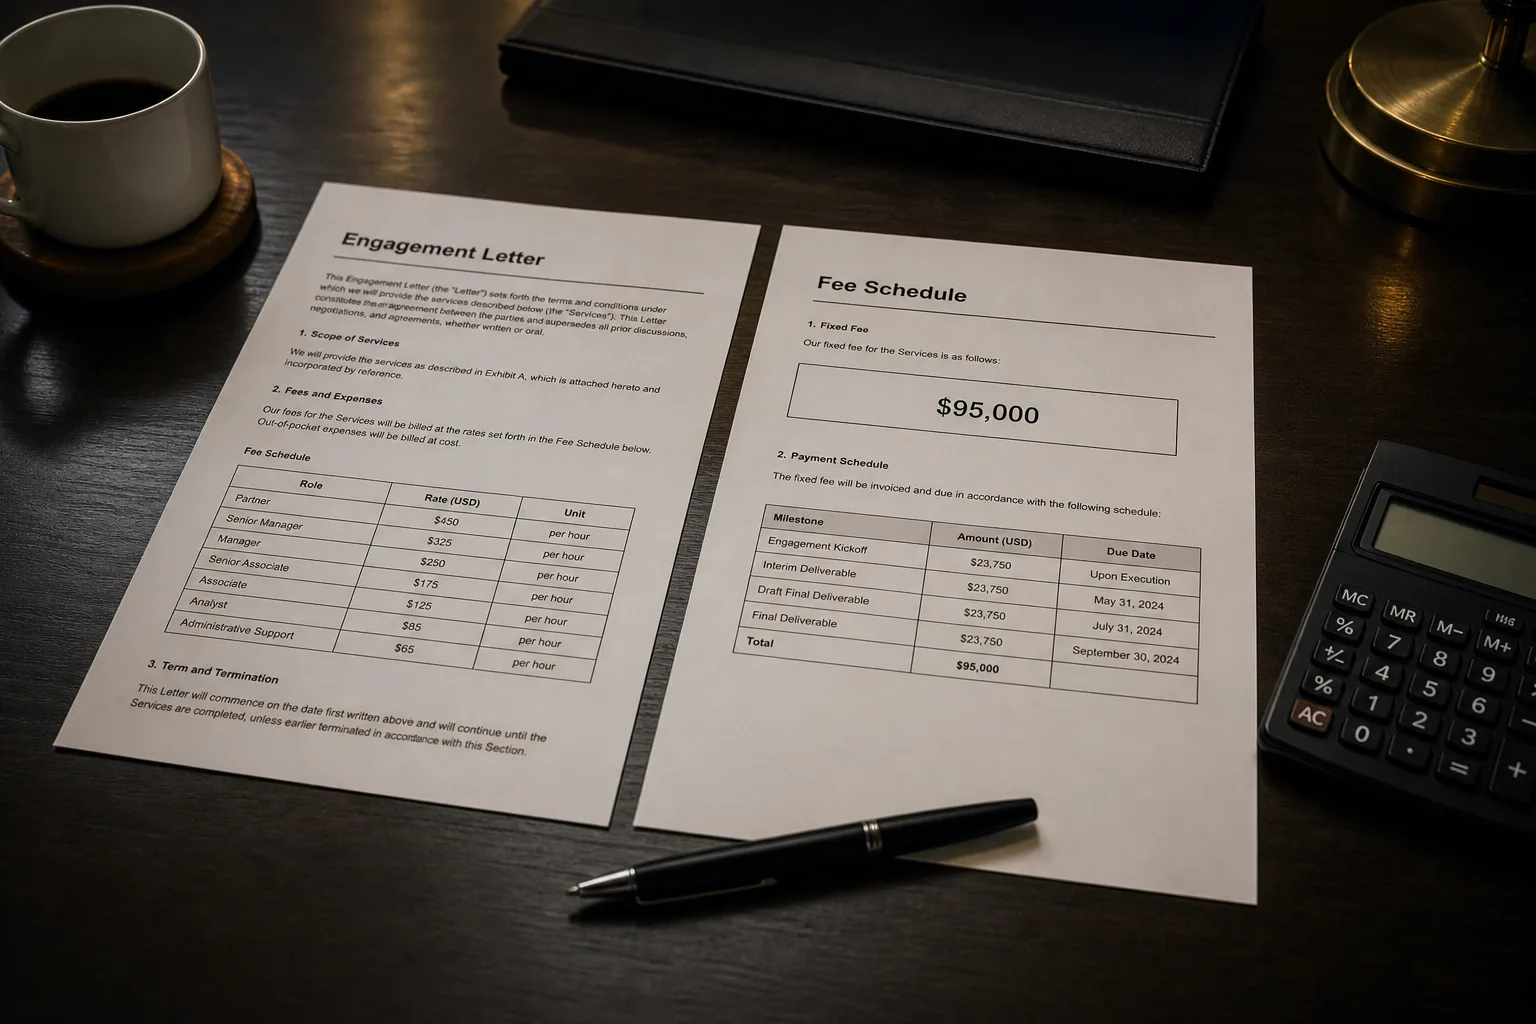
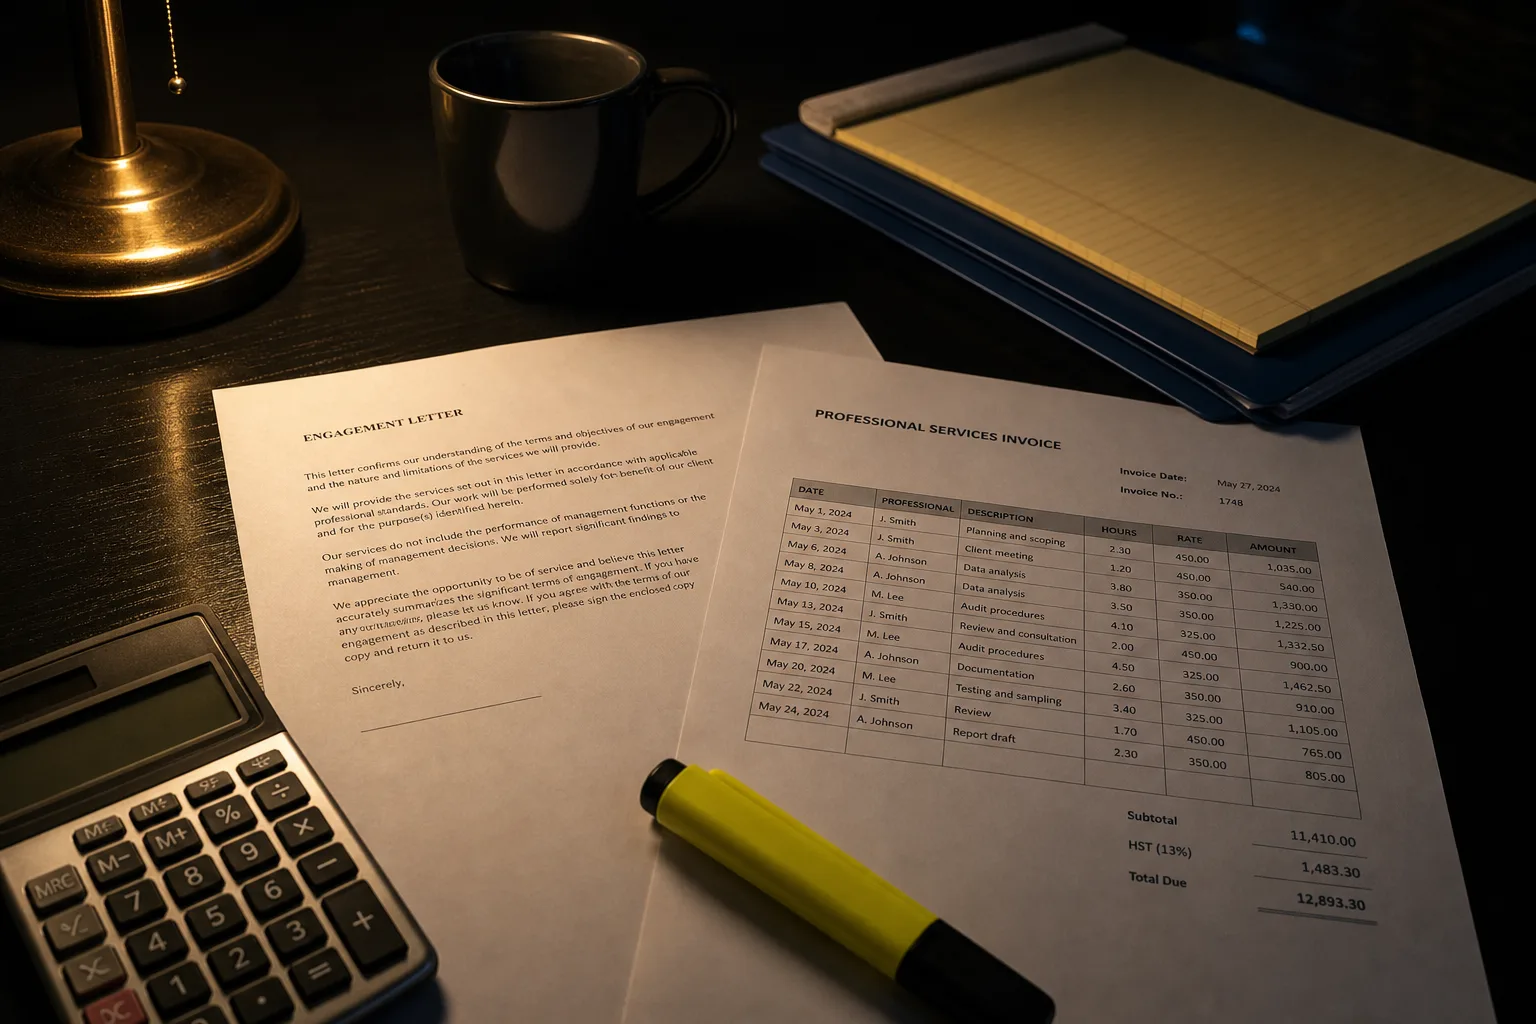
The complaint about hourly billing is old and it is not baseless: a professional paid by the hour has no financial reason to work faster, and the client signing the engagement letter has no way to know, in advance, how many hours the matter will take. A fixed fee looks like the fix. One number, agreed at the start, no surprises. That framing survives because it is true for a particular kind of work, the kind with a defined beginning and end, and it has been quietly losing ground everywhere else for reasons that have less to do with billing ethics than with what the work now takes.
The hourly rate is not paying for time, it is holding the uncertainty
When a firm quotes hourly, the client is carrying the risk that the job runs long. When a firm quotes a fixed fee, the firm is carrying it, and the fee includes a premium for doing so. Neither arrangement is generous. The question is which side is better placed to absorb a bad outcome, and on a contested matter, where the other party controls half the workload, the answer is usually neither, which is why open-ended disputes have stayed on the clock while incorporations, trademark filings, closings, and routine returns moved to flat pricing years ago. The scope is the variable. The billing method follows it.
That distinction explains most of the confusion. Buyers compare an hourly rate against a fixed fee as though they were two prices for the same thing. They are two allocations of the same unknown. A fixed fee on a matter nobody can scope is not a discount; it is either a firm guessing high enough to protect itself, or a firm that will come back with a change order the first time the file turns. Reading the exclusions in the fee agreement tells you more than comparing the headline numbers.
What changed: the hours came out of the routine half of the work
The last few years have compressed the labor in document-heavy, precedent-heavy work. Drafting assistance, template libraries, e-signature and closing platforms, structured intake, and support staff working across time zones have all pushed down the number of billable hours a standard matter actually consumes. A firm that kept billing those matters hourly watched its revenue on them fall even as its output rose, which is a strange result and not a stable one. So the pricing moved. Fixed fees, subscriptions, and monthly retainers spread fastest in exactly the areas where the hours fell hardest, because that is where hourly billing stopped describing the value delivered.
Corporate procurement accelerated it. In-house departments running e-billing systems started refusing to approve line items they could not predict, and outside firms that wanted the panel seat responded with phase-based pricing: a set fee for diligence, another for drafting, another if the matter goes to hearing. Individual clients inherited the vocabulary. When a firm today offers to price a matter by stage rather than by the hour or by a single all-in number, it is applying a structure that large buyers forced into existence, and it is generally the most honest description of what anyone can actually forecast.
The part of the deal that is really a loan
How you pay matters as much as what you pay, and the two are usually bundled together without being labeled. A firm that takes a large retainer up front and draws against it is holding your money before the work exists; a firm that bills monthly in arrears is extending you credit and pricing that somewhere. Deferred arrangements, success fees, and contingency percentages are financing, plainly. The professional funds the work, carries the collection risk, and is compensated for both, which is why an outcome-based percentage almost always exceeds what the same hours would have cost at standard rates. That gap is the interest, even though no one calls it that.
Paying later is the worse deal more often than buyers expect. A flat fee split across the engagement with no stated finance charge is usually cheaper than the same fee put on a card at revolving rates, and cheaper still than a fee-financing loan arranged through a third-party lender, where the professional gets paid in full and you carry a consumer installment obligation with its own origination cost. Ask what the fee is if paid in full at signing, then ask what it is on the payment plan. If those numbers differ, you have found the cost of borrowing, and it belongs in the comparison.
Where the rules limit the choice
Outcome pricing is not available everywhere, and the limits are not arbitrary. Contingency arrangements are restricted or prohibited in areas where tying the fee to the result would distort the professional's judgment or the integrity of a filing, which is why tax practice in particular has narrow boundaries around fees keyed to the size of a refund. The IRS is responsible for the standards governing who may represent taxpayers before it and how those representatives may conduct themselves, and any preparer offering to take a cut of your refund should be able to explain, without hesitation, why that particular arrangement is permitted for that particular engagement.
So the practical test is not philosophical. It is whether the work has an edge you can both see. Ask what the professional needs in order to quote a fixed number, and if the answer is a document review or a title search or a first meeting, buy that piece hourly and take the fixed fee on the rest once the scope is visible. That sequence, a small metered start followed by a priced-out remainder, is how most well-run engagements now begin, and it costs less than committing to either method blind.
Read the fee agreement for three things: what triggers a change order, what happens to unused retainer, and what the total is under each payment schedule. A firm that answers all three in writing has told you where the risk sits, and that is the number worth comparing.