Water in the House and Nobody Billing the Insurer Directly? How the First Two Days Get Paid For Now
A mitigation contractor on how emergency water work used to be billed straight to the carrier, what changed, and what the delay now costs a homeowner who borrows to bridge it.
- Home & Property
- Farah Siddiqui
- 1,076 words, 5 min
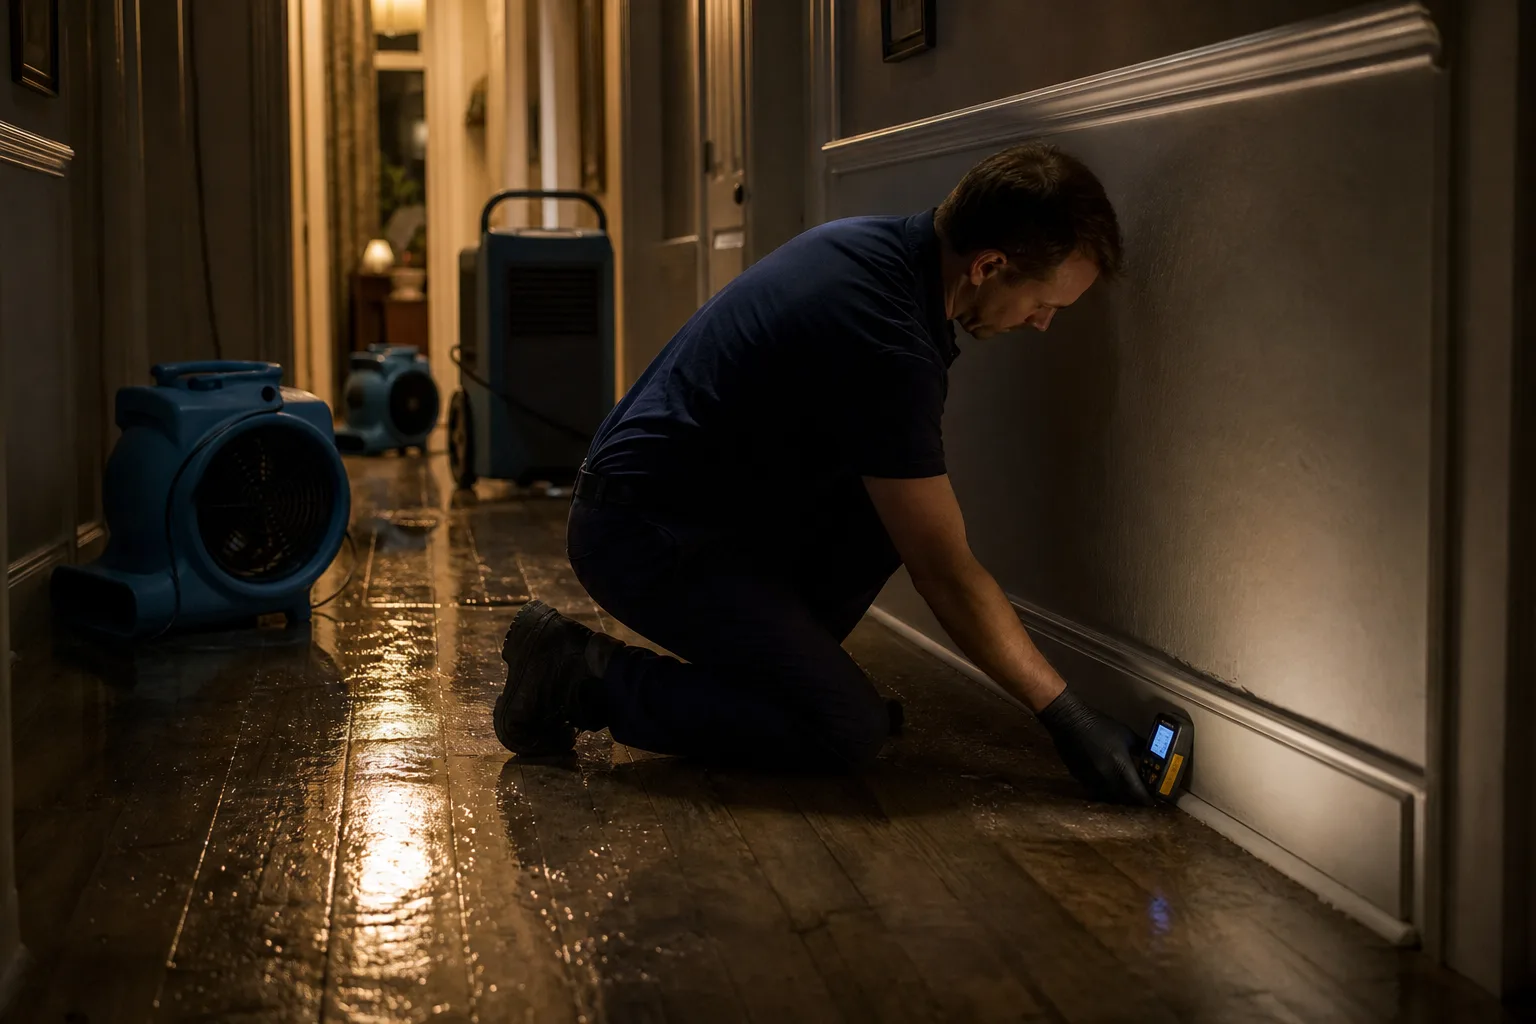
The advice most people carry into a water loss is that the insurer handles it. You call, a crew arrives, the drying happens, and the bill goes somewhere over your head. That was accurate for a long stretch in a lot of markets, and it is still partly accurate today, but the part that changed is the part that costs money: who fronts the cash during the two days when the decisions are made. I put that to a mitigation contractor who has run emergency crews for about twenty years, and who asked to be identified by role rather than company, since he still bids work for several of the carriers described here.
How the direct bill became the default, and for whom
His account of the old arrangement is straightforward. Carriers wanted water out of a structure fast, because a wet house becomes a mold claim and a mold claim becomes a rebuild, so they built networks of vendors who would mobilize on a phone call and invoice the carrier afterward. The homeowner signed a work authorization, sometimes an assignment of benefits, and the money moved between two businesses. "The customer never saw a number until the deductible came up," he said. "That was the selling point of the program, and it worked because the carrier and the contractor both wanted the same thing in the first two days, which was air movers running before anything got worse."
It worked best for people inside those networks. If you called your carrier first and took the referral, you got the frictionless version. If you called a neighbor's contractor at two in the morning because the water was rising, you often got a contract that made you the payer, with reimbursement your problem later. That split has never fully closed, and understanding which side of it you are on within the first few hours is still the single most useful thing a homeowner can establish.
What changed, and why the paperwork got heavier
Three things moved at roughly the same time, in his telling. Several states tightened the rules on assignment of benefits after litigation over inflated emergency invoices, which means the document that used to transfer the claim to the contractor now either does less or requires disclosures and cancellation windows that slow it down. Carriers leaned harder on standardized estimating platforms, so line items and drying times get compared against a database rather than accepted on a contractor's word. And more policies now carry explicit caps on emergency mitigation paid without prior approval.
"None of that was aimed at the homeowner," he said. "It was aimed at the handful of shops that were writing four days of equipment for a two-day job. But the effect on a normal loss is that I need photographs, moisture readings, and a scope agreed with an adjuster before anyone commits to a number, and that takes hours I used to spend just drying the house." The practical result is that documentation now runs alongside the work rather than after it, which is also why the well-run firms show up with a camera and a meter before they show up with equipment.
The forty-eight hours as a payment window
He is firm that the clock everybody talks about is not really a drying clock. Drying takes as long as the assembly takes. The forty-eight hours matter because that is when the payment structure for the whole job gets set, and it is very hard to renegotiate afterward. Whether the carrier issues an emergency advance, whether the crew is billing you or billing them, whether the scope includes removing wet insulation from inside a wall cavity or just running fans in the room: all of that gets decided while the water is still standing.
His advice is to ask the crew chief and the adjuster the same question in the same sentence, which is who is invoiced for the mitigation and who is invoiced for the repairs, since they are frequently two different companies and two different checks. He also says to get the emergency advance requested on the first call rather than the third day. "Carriers can move money quickly when the request is specific," he said. "They move slowly when someone asks for help in general terms. A specific number, tied to a scope, tends to get answered."
What bridging the gap actually costs
This is where the financing question stops being theoretical. If you are fronting the mitigation, you are borrowing for somewhere between a few weeks and a few months, because the mitigation invoice comes due long before the repair settlement lands, and the two are almost never synchronized. A card at a revolving rate carried for two months is an expensive way to buy that time. A home equity line, if one is already open, is usually the cheapest, and the word already is doing most of the work in that sentence, because a new line takes longer to close than a drying job takes to finish.
Contractor-arranged financing sits in between, and he is candid that the quality varies with the shop offering it. Promotional periods that defer interest can be genuinely useful if the settlement arrives inside the window and genuinely punitive if it does not, since deferred interest is typically charged retroactively on the full original balance. The Consumer Financial Protection Bureau oversees the disclosures on that kind of consumer credit, and the disclosure that matters is the one describing what happens on the day the promotion ends. Read that paragraph, then compare it against a realistic estimate of when your carrier will actually pay, which your adjuster can usually give you.
The version that works, he says, is unglamorous. Get the advance requested immediately, keep the mitigation invoice separate from the repair contract, and if you must borrow, borrow against the cheapest facility you already hold rather than the most convenient one offered to you at the kitchen table. Homeowners who do those three things tend to come out of a water loss with the same repair and materially less financing cost.
The mechanics changed for reasons that had almost nothing to do with the person whose floor is wet, and the changes have made the paperwork heavier and the first phone call more consequential. They have also made the money more traceable, which cuts in the homeowner's favor once you know which questions produce a number and which produce a shrug.